
Bezos Bets $12B on the AI That Engineers Hardware
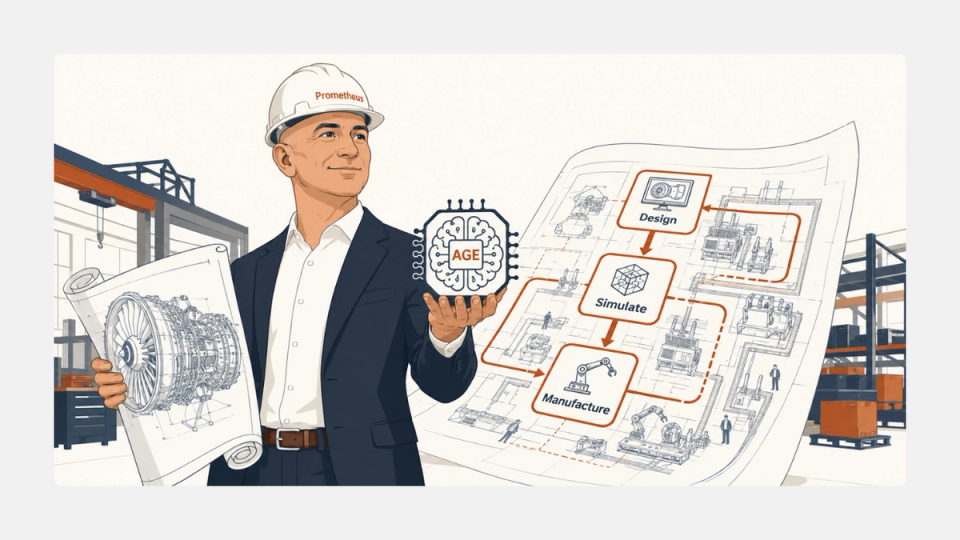
Jeff Bezos and co-founder Vik Bajaj announced on June 11, 2026 that Prometheus, their industrial AI startup, had closed a $12 billion Series B funding round at a $41 billion valuation — making it the largest single funding round for any AI startup targeting the physical world.
The $12B is not going toward another chatbot. Prometheus is building what Bezos calls an "artificial general engineer" — AI software that handles the end-to-end design, simulation, and pre-production workflow for complex physical systems: jet engines, medical devices, semiconductors, and advanced materials. The goal is to compress an engineering cycle that currently takes years into something that takes months.
What Happened
The Series B was backed by JPMorgan Chase, Goldman Sachs, BlackRock, DST Global, and Arch Venture Partners, with Bezos himself contributing to the round. It follows Prometheus's initial $6.2 billion funding when the company launched in late 2025, bringing total capital raised to over $18 billion.
Prometheus has roughly 150 employees across San Francisco, London, and Zurich. Bezos serves as co-CEO alongside Bajaj, a scientist-entrepreneur who previously worked in computational biology and materials science.
The company has no formal ties to Amazon or Blue Origin. Bezos has noted the technology could eventually improve processes at Blue Origin, but that is not the current operating mandate.
Prometheus is not a robotics company. It is a software company building what it describes as a "CAD-plus-factory-floor brain" — autonomous software that handles prototyping, large-scale simulation, and workflow design before a single physical part is manufactured. The product has not been publicly demonstrated.
What It Actually Means
Is "artificial general engineer" just AGI marketing?
Partly, yes. The phrase "artificial general engineer" is deliberately adjacent to "artificial general intelligence" and earns attention. But the actual claim is narrower and more defensible: Prometheus is not promising a reasoning system that matches human intelligence broadly. It is promising a domain-specific AI that matches (or beats) senior mechanical and materials engineers on the specific workflow of designing and simulating complex physical products. That is a hard, real, and commercially valuable problem — and it is not what any of the major foundation model labs are directly targeting.
The contrast matters. OpenAI, Anthropic, and Google are building general-purpose models that happen to be useful for engineering tasks. OpenAI recently admitted Anthropic's safety-first framing was strategically correct — suggesting even the frontier labs are still navigating what their models are actually for. Prometheus makes the opposite bet: a domain-first system, purpose-built for engineering workflows, funded at a scale that lets it pursue proprietary training data from industrial partners rather than crawl the public web.
Does a $41B valuation make sense for 150 employees with no product?
Probably not on conventional software metrics. But Prometheus may not intend to stay a software company. Reports indicate the startup has explored raising additional capital to acquire existing industrial businesses — applying its AI to real manufacturing operations rather than licensing software to factories that may or may not adopt it. That strategy looks more like Bezos's Amazon playbook (own the infrastructure) than the typical SaaS land-and-expand motion.
The comparable here is not OpenAI at $300B. It is Anthropic's compute strategy of securing physical-world assets — reserving the data center capacity needed to validate technology at scale before competitors can. Prometheus is doing the same in manufacturing: securing capital now to own the infrastructure of physical product R&D.
What does "compressing the engineering cycle" actually mean in practice?
Bezos has described the goal as accelerating the "dream-build loop" — the time between an engineer conceiving a design and having a working prototype validated in simulation. For a jet engine component, that cycle currently runs 3–7 years including regulatory review. For a novel semiconductor architecture, it can run 5–10 years from research to tape-out.
If Prometheus's software can collapse even half that timeline, the downstream value is enormous: the first aerospace firm to design turbine blades in 18 months instead of 5 years does not just save money — it structurally outcompetes everyone still on the old timeline. That is the bet Bezos is making with JPMorgan and BlackRock's money.
Prometheus has not disclosed benchmark numbers, proof-of-concept results, or named any industrial partners publicly. That gap is worth flagging. The company may be at early research stage rather than productized software stage, which would make the $41B valuation a very large bet on a team and a thesis, not on demonstrated traction.
Who This Affects
Aerospace and defense engineers: If Prometheus productizes and ships to industry, the downstream pressure on engineering teams is real. Not mass layoffs — Bezos explicitly argues AI productivity gains lead to labor shortages, not unemployment, as growth outpaces headcount reduction — but a significant shift in what a senior engineer's time is worth. Teams that adopt early own the productivity advantage. That pattern is already playing out in software engineering, where 84% of developers now use AI coding tools regularly, and it will hit hardware engineering with the same force.
AI infrastructure investors: The Prometheus raise signals that the next wave of AI capital is not flowing into foundation model labs or software SaaS. It is flowing into domain-specific AI targeting industries with multi-decade engineering cycles. Meta's $145B capex bet targets consumer and enterprise software at scale. Prometheus targets something smaller in addressable market but potentially much higher in per-customer value: the handful of companies globally that design jet engines, medical implants, and next-generation chips.
Competing industrial AI startups: Siemens, Dassault Systemes, and PTC all have existing simulation and CAD software businesses. None of them raised $18 billion to rebuild from first principles with AI. The incumbents have distribution; Prometheus has capital and a founder with a track record of building fast and vertically integrating when needed. That tension will play out over the next 3–5 years.
AI regulation watchers: Industrial AI applied to aerospace and medical device design sits inside the regulatory perimeter of the FAA, FDA, and their European equivalents. An AI that accelerates the design of jet engines is also an AI whose outputs require certification before they fly. Prometheus has not disclosed how it intends to navigate regulatory approval cycles, which remain largely manual regardless of how fast the design phase moves.
What to Watch For Next
In the next 30 days: Any named industrial partner announcement. The $12B raise was news; a customer with a real deployment is proof. Watch for announcements from aerospace primes (Boeing, Airbus, GE Aerospace) or defense contractors.
In the next 90 days: Whether Prometheus pursues the acquisition strategy that has been reported. An industrial acquisition would signal the company is moving into operations, not just software — and would reshape the competitive picture significantly.
In 6 months: Whether the major foundation model labs (OpenAI, Google DeepMind, Anthropic) respond with dedicated industrial verticals, or whether they cede this market to domain-specific players.
The regulatory wildcard: FAA and FDA have not signaled how they will treat AI-generated engineering designs in certification processes. Prometheus's timeline depends partly on regulators moving faster than they historically have.
The Bottom Line
Prometheus is either the most credible bet on physical-world AI since Boston Dynamics, or it is $18 billion raised on the strength of Jeff Bezos's brand before anyone has seen the product. The truth is probably somewhere between the two. What is not in doubt: the thesis is real. Physical product R&D is slow, expensive, and deeply underserved by the current generation of AI tools. Bezos has identified a genuine gap. Whether Prometheus fills it — and whether the $41B valuation is justified — depends on product and proof, neither of which is public yet. Watch the first named customer announcement carefully. That is the tell.